Thursday, November 11, 2010
Tuesday, September 28, 2010
New FHA MIP (Mtg Insur Premium) Changes Take Effect Oct 4th

- Upfront MIP drops to 1.000% of the amount borrowed from 2.250%
- Annual MIP increases to 0.850% of the amount borrowed from 0.500% **
** When putting down less than 5% (LTV > 95%) the annual MIP increases to 0.900% (from 0.550%) of the amount borrowed.
In addition, borrowers will also be required to have a higher credit score than before. The FHA loan is popular because its minimum down payment is 3.5%, whereas most conventional loans require a much higher down payment. FHA will make the premium fee changes on all new case numbers effective October 4, 2010 .
Why is the FHA raising Mortgage Insurance (MI) payments now in this market?
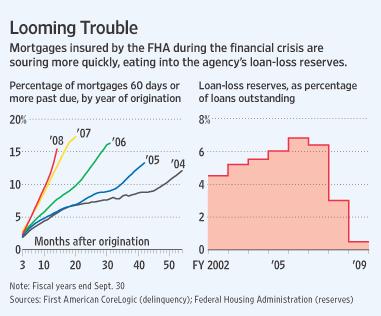
As the graph supports, the FHA’s reserve funds have been rapidly depleting and need shoring up soon to withstand future imminent defaults. Money generated from these changes should help recapitalize and stabilize this government agency. For additional details see FHA BILL_H.R. 5981.
Looking for more on the new FHA MI changes (and a little humor) check out Twist on New Home Buyer Tax.
If you’re unsure of how the new FHA mortgage premiums will impact your mortgage, be sure to call or email your loan officer for help.

Sunday, August 15, 2010
30-year mortgage at lowest rate since 1971
NEW YORK (CNNMoney.com) -- Mortgage rates continued to decline this week, plunging to the lowest level in decades, according to surveys from Freddie Mac and Bankrate. Freddie Mac's weekly report said the 30-year fixed rate slipped to 4.44% for the week ended Thursday, the lowest since the government-backed lender began tracking the rate in 1971. Last week's rates stood at 4.49%, and a year ago it was at 5.29%.
 The 15-year fixed rate fell to 3.92% this week, the lowest since Freddie Mac began tracking it 1991, down from 3.95% last week and from 4.68% a year ago. Adjustable-rate mortgages also declined, with the 5-year rate falling to 3.56% this week, the lowest since 2005 when the lender began tracking it.
 Mortgage tracker Bankrate.com, which surveys large lenders across the country, said the average 30-year fixed loan sank to a record low for the fourth consecutive week, falling to 4.57% from 4.66% the previous week.
The 15-year fixed rate, which is a popular option for refinancing, also fell to the lowest level in the history of Bankrate's 25-year old survey, dipping to 4.06%, from 4.11% the week before. While the 1-year adjustable-rate mortgage held steady at 4.8% for a fourth week, the 5-year adjustable rate mortgage dropped to a record low of 3.92% from 3.95% the previous week.
"Low rates are helping to heal many battered local housing markets by increasing home-purchase activity, said Frank Nothaft, chief economist at Freddie Mac. Mortgage rate applications inched up a modest 0.6% during the week, according to the Mortgage Bankers Association. Applications for purchase rose 0.3% while refinance applications increased 0.6%.
Source: CNNMoney.com -- By Hibah Yousuf, staff reporterAugust 12, 2010
NEW YORK (CNNMoney.com) -- Mortgage rates continued to decline this week, plunging to the lowest level in decades, according to surveys from Freddie Mac and Bankrate. Freddie Mac's weekly report said the 30-year fixed rate slipped to 4.44% for the week ended Thursday, the lowest since the government-backed lender began tracking the rate in 1971. Last week's rates stood at 4.49%, and a year ago it was at 5.29%.


The 15-year fixed rate, which is a popular option for refinancing, also fell to the lowest level in the history of Bankrate's 25-year old survey, dipping to 4.06%, from 4.11% the week before. While the 1-year adjustable-rate mortgage held steady at 4.8% for a fourth week, the 5-year adjustable rate mortgage dropped to a record low of 3.92% from 3.95% the previous week.
"Low rates are helping to heal many battered local housing markets by increasing home-purchase activity, said Frank Nothaft, chief economist at Freddie Mac. Mortgage rate applications inched up a modest 0.6% during the week, according to the Mortgage Bankers Association. Applications for purchase rose 0.3% while refinance applications increased 0.6%.
Source: CNNMoney.com -- By Hibah Yousuf, staff reporterAugust 12, 2010
Tuesday, May 4, 2010
GFE and HUD Settlement Statement Changes

Their intention is to make it easier for buyers to understand what they are getting when they apply for mortgage financing - and to minimize unwanted surprises at the closing table with potentially different (higher) charges on the HUD-1 than what was stated on the GFE.

Scott Rinn, a senior policy analyst with NAR, thinks the new forms will be easier for consumers to understand and that the tolerances [HUD’s term for how much costs can change between the GFE and the HUD-1] at least in theory, should reduce closing-table surprises. The degree of these improvements will discovered over time.
The forms are not particularly intuitive and will need further clarification. Even so, the consensus is that these changes are for the better and (as with most things) will continue to improve over time.
The attached video Changes to GFE and HUD Statement (led by Scott Rinn, our RESPA guru) gives perspective page-by-page on the changes within the two forms that took effect January 1, 2010.
Please contact me with any questions you may have regarding these new RESPA forms.
Thursday, June 4, 2009
Obama's Making Home Affordable Program

 Making Home Affordable Program -- On February 18, 2009, President Obama announced his Making Home Affordable Program, designed to help up to 7-9 million families avoid foreclosure by restructuring or refinancing their mortgages.
In doing so, the plan not only helps responsible homeowners behind on their payments or at risk of defaulting, but prevents neighborhoods and communities from being pulled over the edge too, as defaults and foreclosures contribute to falling home values, failing local businesses, and lost jobs.
For more detailed information, visit www.makinghomeaffordable.gov/.
Information Courtesy: Realtor.org - Government Affairs
Subscribe to:
Posts (Atom)